Smart Budgeting Tips for Millennials: The 2026 Playbook
Mint is gone, budgeting apps now cost real money, and the 50/30/20 rule breaks the moment rent passes half your paycheck. Here is a 2026 budgeting plan for millennials that accounts for all three, with the math written out.

TL;DR: Mint is gone, budgeting apps now cost real money, and 50/30/20 breaks when rent tops half your paycheck. Track spending for 30 days, automate savings after bills clear, fund sinking funds for irregular costs, and clear 20%+ APR debt before chasing savings interest. Consistency beats optimization.
What is a personal spending plan, and why does it matter more at 35 than at 25?
A personal spending plan is a written allocation of your take-home pay across fixed costs, flexible spending, savings, and debt before the month begins. It is not a restriction list — it is a decision made once, in advance, so you stop making forty small decisions under pressure.
The reason it matters more in your thirties and early forties is that the number of fixed obligations multiplies. Rent or a mortgage, childcare, insurance premiums, a car payment, student loans, and aging-parent costs all arrive on schedule whether or not you looked at your balance. In your twenties a bad month is an inconvenience. Later, a bad month can trigger a late fee, a rate hike, and a credit-score dent at the same time.
Which budgeting app should you use now that Mint is gone?
Intuit shut Mint down in early 2024 and migrated users into Credit Karma, which shows accounts and credit data but does not do real category budgeting. If Mint was your system, you need a replacement — and most credible ones now charge a subscription, because free apps funded by product referrals have largely faded.
| Tool | Rough cost | Best for | Weak spot |
|---|---|---|---|
| YNAB | About $109/year or $15/month, with a free trial | People who want every dollar assigned a job | Steep learning curve; the priciest option |
| Monarch Money | Around $100/year | Couples sharing one dashboard and net-worth tracking | Less prescriptive than YNAB about behavior |
| Rocket Money (formerly Truebill) | Free tier; premium is user-chosen, roughly $6–$12/month | Finding and canceling forgotten subscriptions | Budgeting features are thinner than the cancellation tools |
| PocketGuard | Free tier plus a paid plan | A simple "what's safe to spend today" number | Limited depth for complex households |
| Spreadsheet | Free | Irregular income, side businesses, control freaks | Manual entry; you will skip weeks |
Decision rule: a $109/year app has to save you about $9 a month just to break even. Give any paid tool three full months. If it has not surfaced a single expense you would otherwise have missed, cancel it and move to a free tier or a spreadsheet. Paying for awareness you are not using is just another subscription.
Does the 50/30/20 rule still work when rent eats half your paycheck?
Use 50/30/20 as a diagnostic, not a commandment. The split — 50% needs, 30% wants, 20% savings and debt payoff — is a useful benchmark, but in expensive metros housing alone can consume 35–45% of take-home pay, which makes the 50% "needs" bucket mathematically impossible before you have bought a single grocery.
When that happens, do not shave the savings line to make the ratio work. Run the split you can actually hit — 60/20/20 or even 65/15/20 — and treat the overage as a structural signal. A needs number above 55% is a housing, transportation, or income problem. It is almost never a latte problem, and pretending otherwise is why so many budgets collapse in week three.
The honest exception
This framework does not apply cleanly if your income is irregular. Freelancers, commission earners, and gig workers should budget from their lowest month in the past twelve, not their average, and treat everything above that baseline as money routed straight to taxes, reserves, and goals.
How do you automate savings without triggering overdrafts?
Schedule the transfer one to two days after payday, not on it — and keep a small cushion in checking. The classic "pay yourself first" advice is sound, but the standard implementation fires the savings transfer at 9 a.m. on payday, before rent, utilities, and card autopay clear. The result is a $35 overdraft fee that erases the month's interest several times over.
Two refinements our team recommends:
- Split the pull. Two transfers of $100 mid-month and month-end fail more gracefully than one $200 hit on the 1st.
- Keep a floor. Leave one week of typical spending in checking permanently and never count it as available.
Where should the money land? A high-yield savings account at an online bank, held separately from your checking so it takes a deliberate transfer to reach. As an illustration only: $50 a week, at a rate near 4% APY, comes to roughly $14,000 after five years — about $13,000 of deposits plus $1,300 or so of interest. The deposits do the heavy lifting. Rates move, so the exact figure will differ.
What is the most expensive budgeting mistake millennials make?
Saving aggressively while carrying a credit card balance at 20%+ APR. It feels responsible and it is quietly expensive. Carry $5,000 on a card at 22% and interest runs somewhere near $1,100 a year; the same $5,000 in a savings account at 4% earns roughly $200. You are paying about $900 a year for the comfort of seeing a larger savings balance.
The sequence that actually works: build a starter buffer of $1,000–$2,000 so a flat tire does not go back on the card, keep contributing enough to capture any employer retirement match (that match is an immediate return you cannot replicate), then throw everything else at the highest-rate balance until it is gone. Only after that does building the full emergency fund take priority again.
How do you stop irregular expenses from wrecking a good month?
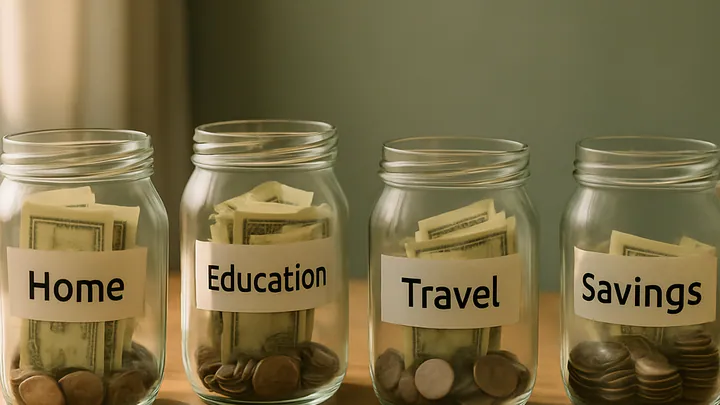
Pre-fund them. Car registration, insurance premiums, annual software renewals, holiday gifts, and vet visits are not emergencies — they are predictable costs that simply do not arrive monthly. Divide each annual amount by twelve and move that sum into a labeled savings bucket every month so the bill is already paid for when it lands.
This is the single highest-leverage habit for people who "budget fine until something happens." Our full walkthrough on setting up sinking funds without panic covers how to size each bucket and how many to run before the system gets unwieldy.
Which spending categories are actually worth cutting?
Focus on recurring costs and the two categories most households overspend without noticing: groceries plus takeout, and clothing. One-off cuts save once; structural cuts save every month for years.
- Subscriptions. Audit every recurring charge across the last 90 days of statements — not just this month, since annual renewals hide from a 30-day view. Cancel anything you have not opened in eight weeks.
- Food. A repeatable weekly plan beats willpower. Our guide to fast, balanced sheet-pan dinners exists partly because the cheapest meal is the one you already have ingredients for.
- Clothing. Impulse apparel buying is a budget leak with a wardrobe attached. A 30-piece capsule wardrobe reduces both the spend and the decision fatigue.
- Travel. Fewer, longer trips generally cost less per day than frequent short ones; slow travel is a budgeting strategy as much as a style choice.
One caveat on cashback and coupon browser extensions: they are useful, but they are paid commissions by the retailers they route you to. That is a legitimate business model, not a scandal — just remember the extension has no incentive to tell you the best purchase is no purchase.
How much should your emergency fund be, and where should it sit?
Three to six months of essential expenses — rent, utilities, food, insurance, minimum debt payments — not three to six months of total spending. Calculating from your full lifestyle number inflates the target so much that many people give up before month one.
| Situation | Target | Why |
|---|---|---|
| Salaried, dual income, in-demand field | 3 months | Two income streams; shorter expected job search |
| Single income, salaried | 4–6 months | No second paycheck to absorb a gap |
| Freelance, commission, or seasonal | 6–9 months | Income varies by design; no severance or unemployment certainty |
| Dependents or a mortgage | 6+ months | Fixed obligations that cannot be scaled back quickly |
Keep it in a high-yield savings account — liquid, FDIC-insured, and separate from daily checking. Do not keep it in investments you would have to sell at a loss during the exact downturn that cost you the job.
How often should you revisit the plan?
Fifteen minutes a month, plus a full rebuild after any life change. The monthly check answers three questions: what did I overspend, what did I forget to fund, and what changes next month? That is it. Budget reviews fail when people turn them into hour-long spreadsheet projects nobody wants to repeat.
A full rebuild — starting from a blank allocation — belongs after a raise, a move, a lease renewal, a new job, or a new family member. Old numbers describe an old life, and running last year's categories against this year's costs is how people end up convinced that budgeting "doesn't work for them."
What should you do in the next 30 days?
Run this sequence in order. It takes about two hours of total effort spread across a month.
- Days 1–3: Pull 90 days of statements. List every recurring charge. Cancel what you do not use.
- Day 4: Calculate your essential monthly number. That figure drives everything else.
- Day 5: Open a separate high-yield savings account and set one automatic transfer for two days after payday.
- Days 6–30: Track spending in one tool — app or spreadsheet, pick one and stop shopping for tools.
- Day 30: Compare actual spending to your assumed budget. The gap is your real starting point.
Financial education helps, but treat it as a supplement rather than a substitute for doing the arithmetic on your own numbers. No podcast knows your rent.
Key takeaways
- Mint no longer exists; choose one replacement deliberately and give it 90 days before judging it.
- 50/30/20 is a diagnostic. If needs exceed 55% of take-home pay, the answer is housing or income — not smaller discretionary cuts.
- Automate savings for one to two days after payday, never on payday, and keep a checking floor to avoid overdraft fees.
- Clear 20%+ APR debt before building beyond a $1,000–$2,000 starter buffer, while still capturing any employer match.
- Sinking funds for predictable irregular costs prevent most "my budget fell apart" months.
- Review monthly in 15 minutes; rebuild from scratch after any real life change.
This article is for general information only and is not financial advice. Interest rates, app pricing, and product availability change. Consult a qualified financial professional about your specific circumstances before making investment, lending, or debt-repayment decisions.
Frequently asked questions
Is Mint still available for budgeting?
No. Intuit shut Mint down in early 2024 and moved users into Credit Karma, which tracks accounts and credit but does not offer full category budgeting. If you are still searching for Mint, your realistic replacements are Monarch Money, YNAB, Rocket Money, PocketGuard, Copilot, or a spreadsheet.
Does the 50/30/20 rule still work in 2026?
It works as a diagnostic, not a mandate. If your needs exceed 50% of take-home pay — common in high-rent metros — do not force the numbers. Run a 60/20/20 or 65/15/20 split, protect the savings line first, and treat the gap as a signal to work on housing costs or income rather than on coffee.
How big should my emergency fund be?
Three to six months of essential expenses is the standard range, but the right number depends on your income stability. Salaried workers in stable, in-demand fields can sit near three months; freelancers, commission earners, single-income households, and anyone supporting dependents should aim for six to nine.
Should I save or pay off credit card debt first?
Build a small starter buffer of roughly $1,000 to $2,000, then attack high-interest debt. Carrying a balance at 20%+ APR while earning around 4% in savings costs you the difference every month — on $5,000 that gap is several hundred dollars a year. Keep contributing to any employer retirement match throughout.
Is a paid budgeting app worth it?
Only if it changes your behavior. An app at roughly $100 a year needs to save you about $9 a month to break even. If you have used it for three months and found nothing you would have missed, switch to a free tool or a spreadsheet.
Why does automating savings sometimes cause overdrafts?
Because the transfer fires on payday, before rent, utilities, and card autopay clear. Schedule your savings transfer one to two days after payday and keep a small buffer in checking, or split the transfer across two smaller pulls per month.
What are sinking funds and why do they matter?
A sinking fund is a small monthly amount set aside for a known, irregular expense — car registration, insurance premiums, holidays, annual subscriptions. They matter because these predictable costs are what usually break an otherwise sound monthly budget.
How often should I review my budget?
Do a 15-minute check every month and a full rebuild after any life change: a raise, a move, a new job, a baby, a lease renewal. Monthly reviews catch drift; rebuilds catch structural changes your old numbers no longer describe.